Asset GuideLearn
🏢 What is a Brazilian REIT (FII)
Become a co-owner of malls, warehouses and office towers with little money and collect your share of the rent every month. Short lessons with video, slides and a quiz.
- 60lessons
- 652slides
- ~284min
- 3levels
What you will learn
- What a FII is and what a share is
- Where the monthly income comes from
- When you pay tax — and when you don't
- How to assess and pick a fund
The learning path
Three levels and their modules, from zero to advanced. Every lesson has a short video, the slides and a quick quiz.
60 of 60 lessons published
From zero: what it is, how it pays and where to buy it.
4 modules · 18 of 18 lessons publishedB1Module B1What a FII is4/4
 B1.1Start hereLesson B1.1What is a real estate fund, anyway?Thousands of co-owners, one big property and a share worth a few reais.12 slides · ~5 min · quiz at the end
 B1.2Lesson B1.2Why you own a share, not the buildingThe property is in the bank's name but belongs to unitholders — and the law builds a wall between them.12 slides · ~5 min · quiz at the end
 B1.3Lesson B1.3Where does the monthly income come from?From the tenant's rent to cash in your account — math included.12 slides · ~5 min · quiz at the end
 B1.4Lesson B1.4FII, direct rental or fixed income?Apartment, CDB or FII: each wins on one yardstick — and all of them swing.12 slides · ~5 min · quiz at the end
B2Module B2Who runs the fund4/4
- B2.1Lesson B2.1Who does what inside an FIITwo essentials, a control team and your broker on the outside.10 slides · ~4 min · quiz at the end
 B2.2Lesson B2.2Administrator: the owner on paperThe properties are in its name — and so is the responsibility.10 slides · ~4 min · quiz at the end
 B2.3Lesson B2.3Manager: who decides what to buySame warehouse, two managers, a 22% gap in income.11 slides · ~5 min · quiz at the end
 B2.4Lesson B2.4The meeting: where unitholders decide tooYour share votes — and the calls that matter most go through the meeting.11 slides · ~5 min · quiz at the end
B3Module B3The types of FII4/4
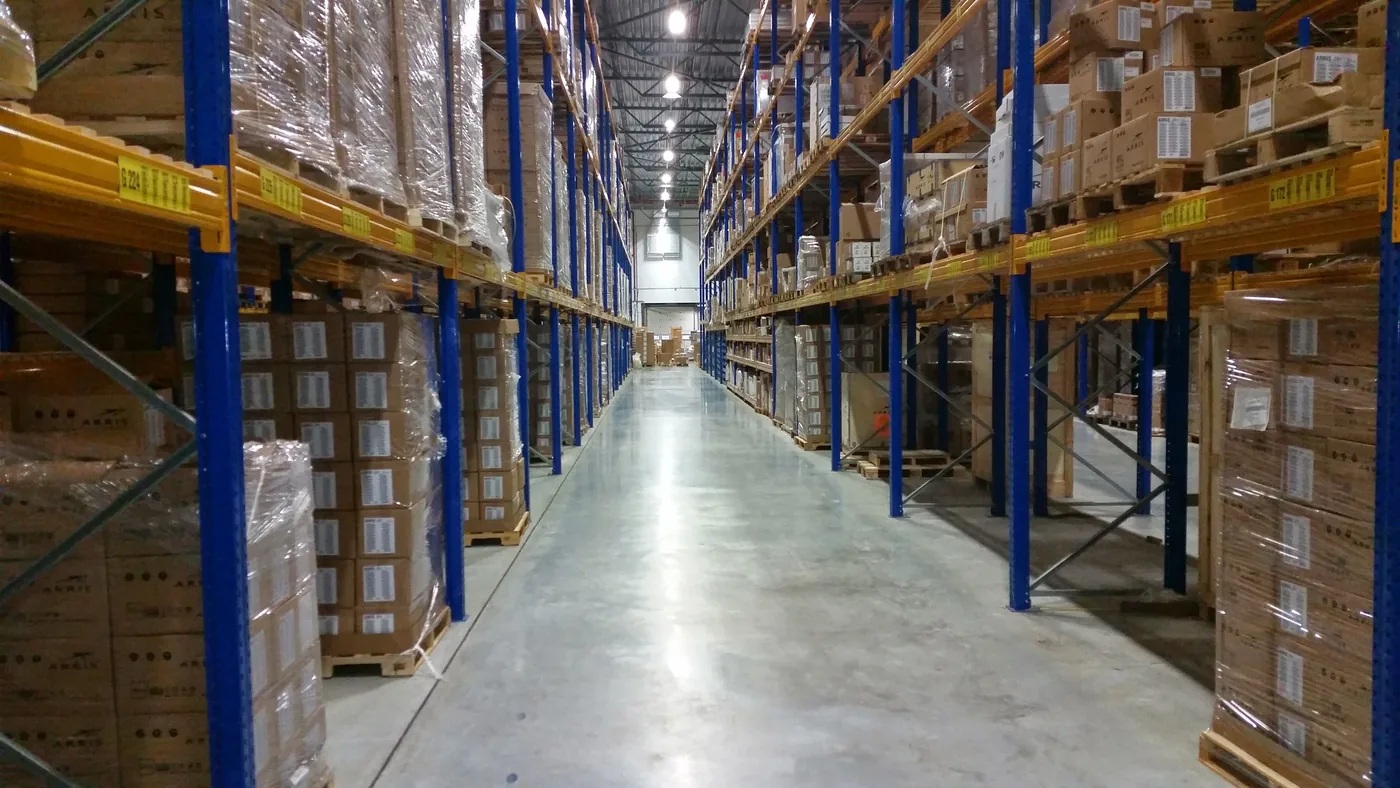 B3.1Lesson B3.1Brick funds: the fund that owns buildingsWarehouse, mall, office: income comes from rent, and the risk changes with the building.11 slides · ~5 min · quiz at the end
 B3.2Lesson B3.2Paper funds: the fund that lends moneyNo building to rent: the fund lends, collects interest and depends on the borrower paying.12 slides · ~5 min · quiz at the end
 B3.3Lesson B3.3Funds of funds and hybridsOne share, many funds inside — and two fees along the way.11 slides · ~5 min · quiz at the end
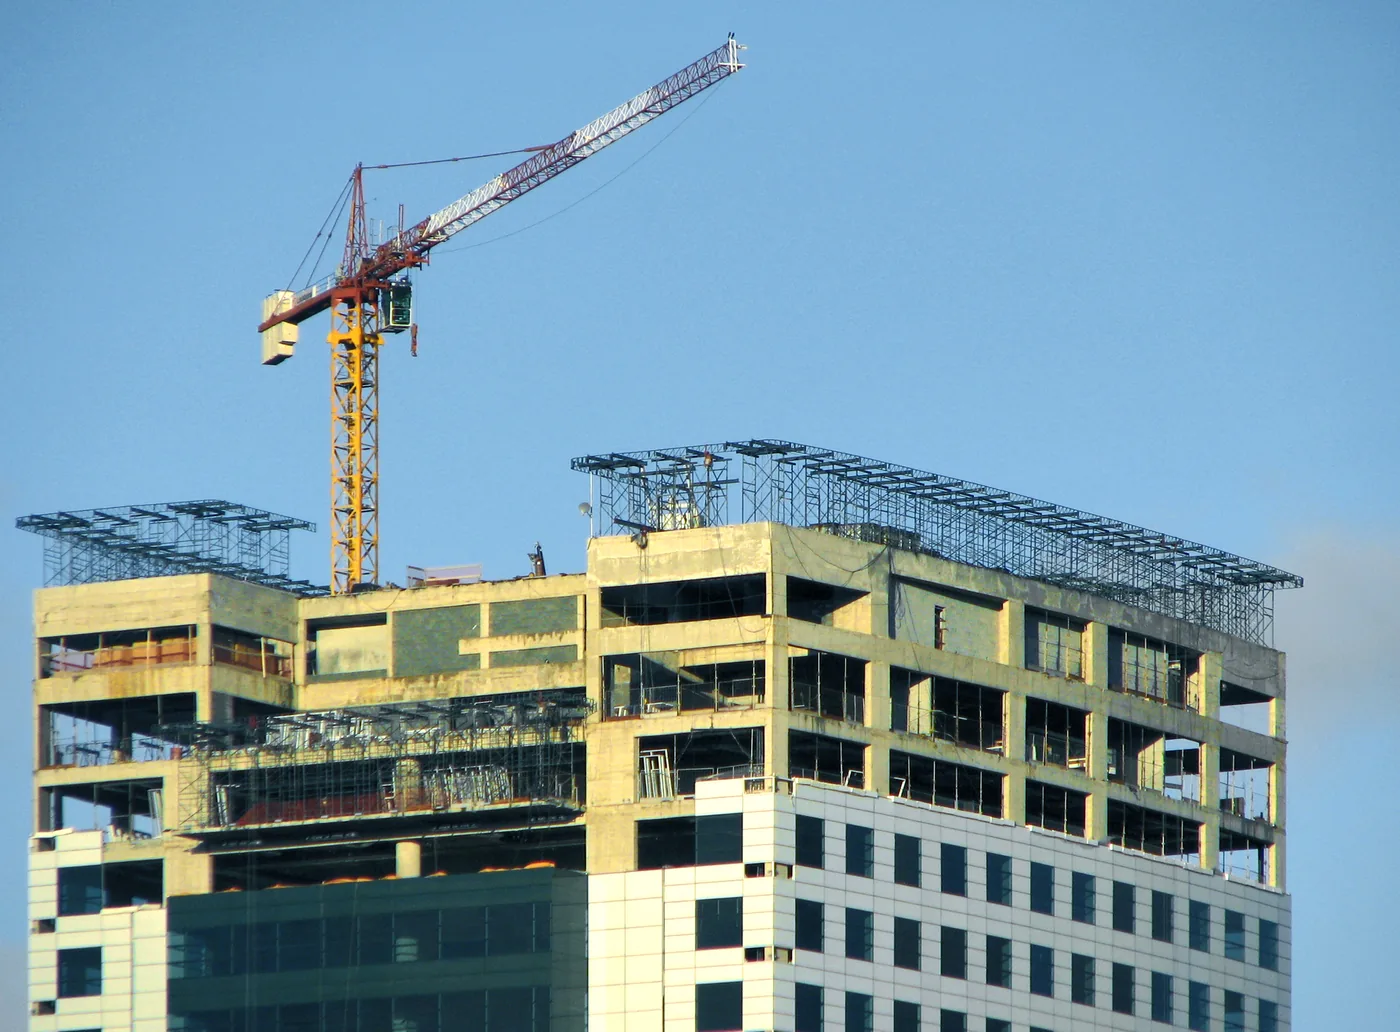 B3.4Lesson B3.4Development, Fiagro and niche typesThe fund that builds, the cost of delays and the Fiagro, the agribusiness fund under the FII law.11 slides · ~5 min · quiz at the end
B4Module B4Your first share6/6
 B4.1Lesson B4.1How to buy your first shareBroker, ticker ending in 11, limit order: your first buy without surprises.11 slides · ~5 min · quiz at the end
 B4.2Lesson B4.2Record date, ex-date and paymentWho gets the month's income — and why the share price takes it out on the ex-date.11 slides · ~5 min · quiz at the end
 B4.3Lesson B4.3How long does it take to sell and get paid?No redemption: to exit, someone buys your share — and the cash arrives at T+2.10 slides · ~4 min · quiz at the end
 B4.4Lesson B4.4Why does the share price go up and down?Same rent, share down 20%: the math that separates interest rates from trouble at the fund.11 slides · ~5 min · quiz at the end
 B4.5Lesson B4.5Is a FII safe? Is there a guarantee?No deposit insurance, no redemption, no guaranteed income — and what still protects you.11 slides · ~5 min · quiz at the end
 B4.6Lesson B4.6Is FII income tax-free? Almost alwaysIncome is tax-free under four conditions; profit on a sale pays 20%, with no R$ 20k stock allowance.11 slides · ~5 min · quiz at the end
How to assess: metrics, fund types and risks.
5 modules · 22 of 22 lessons publishedI1Module I1How a FII is born and grows4/4
 I1.1Lesson I1.1How a Brazilian REIT is createdA REIT's assembly line — and why registration is not a quality seal.11 slides · ~5 min · quiz at the end
 I1.2Lesson I1.2What does it cost to structure and raise a REIT?A real prospectus opened up: 3.24% of the offering is cost, and nearly all of it is commission.10 slides · ~4 min · quiz at the end
- I1.3Lesson I1.3Public offerings: IPOs and follow-onsThe first raise and the ones after — and why issuing is not a sign of health.11 slides · ~5 min · quiz at the end
 I1.4Lesson I1.4Pre-emptive rights, leftovers and dilutionIf the fund issues shares and you don't buy: what falls and what stays.10 slides · ~4 min · quiz at the end
I2Module I2What the fund can (and can't) do3/3
 I2.1Lesson I2.1Allowed and forbidden: the REIT portfolioThe shelf of what the manager may buy — and what stays behind glass.10 slides · ~4 min · quiz at the end
 I2.2Lesson I2.2The 95% rule: cash, not accountingThe fund pays out on cash that came in — revaluation does not count.11 slides · ~5 min · quiz at the end
 I2.3Lesson I2.3Reserves, reinvestment and capital returnsGains become income; principal may come back to you — and that is not income.11 slides · ~5 min · quiz at the end
I3Module I3The fund's documents3/3
 I3.1Lesson I3.1The manager's report: must you read it?A ten-minute checklist and the habit that catches hidden setbacks.10 slides · ~4 min · quiz at the end
 I3.2Lesson I3.2Monthly filings and material facts: the mandatory onesThe calendar of what the fund must disclose — and the alarm outside it.10 slides · ~4 min · quiz at the end
 I3.3Lesson I3.3The bylaws: the contract that rules everythingThe contract that says what the manager may do — and what needs your vote.10 slides · ~4 min · quiz at the end
I4Module I4Analysis indicators9/9
- I4.1Lesson I4.1Dividend yield: the most misleading numberA high yield may be a property sale or a falling price, not a better fund.11 slides · ~5 min · quiz at the end
- I4.2Lesson I4.2P/BV: cheap compared to what?P/BV 0.80 is only a discount if book value is realistic.11 slides · ~5 min · quiz at the end
 I4.3Lesson I4.3Does the dividend fit the cash the fund generates?Steady income may be burning reserves — count the months left.11 slides · ~5 min · quiz at the end
- I4.4Lesson I4.4Physical and financial vacancy are not the sameLosing the priciest space cuts income more than the area suggests.11 slides · ~5 min · quiz at the end
- I4.5Lesson I4.5Defaults, grace periods and rent discountsA 100% occupied building can still collect half the rent.10 slides · ~4 min · quiz at the end
- I4.6Lesson I4.6Typical and atypical leases and average termA long lease guarantees a penalty, not income — and the penalty can vary 40×.11 slides · ~5 min · quiz at the end
 I4.7Lesson I4.7Paper FIIs: index, spread, collateral, ratingPaper funds lose too: when the borrower stops paying and collateral falls short.11 slides · ~5 min · quiz at the end
- I4.8Lesson I4.8Leverage: when the fund owes moneyDebt doesn't shrink: the whole property drop lands on shareholders.12 slides · ~5 min · quiz at the end
 I4.9Lesson I4.9Concentration: one tenant can bring it all down15 properties with 60% of revenue from one tenant isn't diversification.11 slides · ~5 min · quiz at the end
I5Module I5Income tax for unitholders3/3
- I5.1Lesson I5.1The tax exemption requirements, one by oneThree locks decide whether your REIT income is tax-free.10 slides · ~4 min · quiz at the end
 I5.2Lesson I5.2Sold REIT shares: 20%, DARF and lossesFrom average price to a paid DARF, with losses in the right vault.12 slides · ~5 min · quiz at the end
 I5.3Lesson I5.3How to report REITs on the annual tax returnWhat you own, what you received and what you sold, each in its section.11 slides · ~5 min · quiz at the end
Reading reports, valuation and portfolio building.
5 modules · 20 of 20 lessons publishedA1Module A1Interest, price and value3/3
- A1.1Lesson A1.1Why interest rates move the share priceThe fraction linking Treasury yields to your share price.11 slides · ~5 min · quiz at the end
- A1.2Lesson A1.2Debt and property REITs in each rate cycleWhen rates rise or fall, who gains income and who gains price.11 slides · ~5 min · quiz at the end
- A1.3Lesson A1.3Fair value: cap rate, replacement cost and cash flowThree yardsticks for a fund's value, and what to do when they clash.12 slides · ~5 min · quiz at the end
A2Module A2Governance: the unitholder's power4/4
 A2.1Lesson A2.1Simple and qualified quorum in practiceHow many votes each decision needs, and why a majority sometimes isn't enough.11 slides · ~5 min · quiz at the end
- A2.2Lesson A2.2Can the fund change its type later?A fund is what its bylaws say, and bylaws change at a meeting.11 slides · ~5 min · quiz at the end
 A2.3Lesson A2.3How to replace the manager or administratorA bad manager can be removed: the rule exists, the hard part is the votes.11 slides · ~5 min · quiz at the end
- A2.4Lesson A2.4Representative, proxies and the minority voiceThree keys small shareholders hold, and almost nobody uses.11 slides · ~5 min · quiz at the end
A3Module A3Can the manager destroy your capital?5/5
 A3.1Lesson A3.1How much the manager and administrator earnFees come out before your income, and the fee base shapes the incentive of whoever charges it.11 slides · ~5 min · quiz at the end
 A3.2Lesson A3.2The manager's interest is not always yoursThe manager almost always wants what you want. Here are the moments when not.11 slides · ~5 min · quiz at the end
 A3.3Lesson A3.3Can a fund cheat its investors?Selling below appraisal: when it is management, a mistake or a serious violation.11 slides · ~5 min · quiz at the end
 A3.4Lesson A3.4The safeguards: appraisal, meeting, CVM and courtsThere are real safeguards against the manager, and every one has a gap.11 slides · ~5 min · quiz at the end
 A3.5Lesson A3.5Is choosing the manager worth more than the dividend?Dividend alone is the rear-view mirror; manager alone is faith. Judge both with data.11 slides · ~5 min · quiz at the end
A4Module A4Events that change the fund4/4
 A4.1Lesson A4.1Discounted share issues: who pays the billNew shares sold at a discount: the discount comes out of existing holders' book value.10 slides · ~4 min · quiz at the end
 A4.2Lesson A4.2Mergers, takeovers and spin-offs: who wins?When two funds become one, the exchange ratio decides who keeps the discount.10 slides · ~4 min · quiz at the end
- A4.3Lesson A4.3Liquidation: what happens to your moneyIf the fund ends, you get what the property sales bring in, in installments and with tax withheld.10 slides · ~4 min · quiz at the end
 A4.4Lesson A4.4Share buybacks and the rules under debateWith shares below book value, buying back and cancelling can lift value for those who stay.10 slides · ~4 min · quiz at the end
A5Module A5Building and managing your portfolio4/4
 A5.1Lesson A5.1The four risks this site measures“Is this fund risky?” That's four questions, each with its own score.11 slides · ~5 min · quiz at the end
 A5.2Lesson A5.2How many FIIs to own and how to diversifyDiversifying means spreading sources of risk, not collecting tickers.10 slides · ~4 min · quiz at the end
 A5.3Lesson A5.3How much to invest to live off the income?Living off income forever means spending only the real return and reinvesting inflation.11 slides · ~5 min · quiz at the end
 A5.4Lesson A5.4The unitholder's routine: monitor, react, sellAfter buying: a short routine, a response to each event and real reasons to sell.11 slides · ~5 min · quiz at the end
Further reading
Go deeper in text and look at real funds.
Frequently asked questions
What is a Brazilian Real Estate Investment Trust (FII)?
It is a fund that pools money from many investors to buy real estate or real-estate securities. By buying a share you become a co-owner of those properties and receive your portion of the rent every month, without buying a whole property.
Do Brazilian REITs pay income tax?
For individuals, monthly distributions are income-tax exempt when the fund trades only on the exchange and has at least 100 unitholders, and the investor holds less than 10% of the shares (Law 11,033/2004, in force as of 09/2026). Capital gains on selling shares are taxed at 20%.
Why does a Brazilian REIT ticker end in 11?
By B3 convention, real estate fund shares use the suffix 11, like MXRF11, HGLG11 and XPML11. But 11 alone is not proof: ETFs and company units (such as TAEE11) use it too, so check the asset name.
What types of FII are there?
Brick funds own physical properties (malls, warehouses, offices) and live on rent. Paper funds lend to the real estate sector by buying CRIs and live on interest. Funds of funds buy shares of other FIIs, and hybrids mix both.
Is FII income guaranteed?
No. Income depends on the rent or interest the fund collects and changes month to month. Vacancy, defaults and high interest rates can cut both the income and the share price, which moves every day on the exchange.
Image credits
- Rodrigo.Argenton · Wikimedia Commons · CC BY-SA 4.0 — Wikimedia Commons
- Pixabay · Pexels · Pexels License — Pexels
- Buffy May · Wikimedia Commons · CC BY-SA 2.0 — Wikimedia Commons
- Luiz Pantoja · Wikimedia Commons · CC BY 2.0 — Wikimedia Commons
- Pedu0303 · Wikimedia Commons · CC0 1.0 — Wikimedia Commons
- Alena Darmel · Pexels · Pexels License — Pexels
- Aaaatu · Wikimedia Commons · CC BY-SA 4.0 — Wikimedia Commons
- ProjectManhattan · Wikimedia Commons · CC BY-SA 3.0 — Wikimedia Commons
- Handi Boyz LLC · Pexels · Pexels License — Pexels
- Karola G · Pexels · Pexels License — Pexels
- Wilfredor · Wikimedia Commons · CC0 1.0 — Wikimedia Commons
- Gaf.arq · Wikimedia Commons · CC BY-SA 3.0 — Wikimedia Commons
- Wilfredor · Wikimedia Commons · CC BY-SA 4.0 — Wikimedia Commons
- Matheus Bertelli · Pexels · Pexels License — Pexels
- Aaaatu · Wikimedia Commons · CC BY-SA 4.0 — Wikimedia Commons
- Leeloo The First · Pexels · Pexels License — Pexels
- Andrea De Santis · Pexels · Pexels License — Pexels
- Tara Winstead · Pexels · Pexels License — Pexels
- Breather (Unsplash) · Wikimedia Commons · CC0 — Wikimedia Commons
- Autor anônimo (Unsplash) · Wikimedia Commons · CC0 — Wikimedia Commons
- igorovsyannykov · Wikimedia Commons · CC0 — Wikimedia Commons
- Wilfredor · Wikimedia Commons · CC BY-SA 4.0 — Wikimedia Commons
- KMR Photography · Wikimedia Commons · CC BY 2.0 — Wikimedia Commons
- stevepb · Wikimedia Commons · CC0 — Wikimedia Commons
- Negative Space · Wikimedia Commons · CC0 — Wikimedia Commons
- Autor não identificado · Wikimedia Commons · CC0 — Wikimedia Commons
- Blogtrepreneur · Wikimedia Commons · CC BY 2.0 — Wikimedia Commons
- stevepb · Wikimedia Commons · CC0 — Wikimedia Commons
- Blogtrepreneur · Wikimedia Commons · CC BY 2.0 — Wikimedia Commons
- Tom Fisk · Pexels · Pexels License — Pexels
- Pixabay · Pexels · Pexels License — Pexels
- PNW Production · Pexels · Pexels License — Pexels
- Christina Morillo · Pexels · Pexels License — Pexels
- Christina Morillo · Pexels · Pexels License — Pexels
- Dave Dugdale · Wikimedia Commons · CC BY-SA 2.0 — Wikimedia Commons
- Breather · Wikimedia Commons · CC0 — Wikimedia Commons
- perzon seo · Wikimedia Commons · CC BY 2.0 — Wikimedia Commons
- Joe Gratz · Wikimedia Commons · CC0 — Wikimedia Commons
- SnowFire · Wikimedia Commons · CC BY 4.0 — Wikimedia Commons
- LeoNado10 · Wikimedia Commons · CC BY-SA 4.0 — Wikimedia Commons
- Willi Heidelbach · Wikimedia Commons · CC BY 2.0 — Wikimedia Commons
- Mike Haw · Wikimedia Commons · CC BY 2.0 — Wikimedia Commons
- Dat doris · Wikimedia Commons · CC BY-SA 4.0 — Wikimedia Commons
- Caroline Attwood · Wikimedia Commons · CC0 — Wikimedia Commons
- Kevin Schneider · Wikimedia Commons · CC0 — Wikimedia Commons
- Eric Rothermel · Wikimedia Commons · CC0 — Wikimedia Commons
Educational content, written for learners. Not investment advice.
📘 What it actually is
Imagine a mall costs R$ 500 million. No single person buys one alone. So money from thousands of investors is pooled, the mall is purchased, and it's divided into small pieces called shares. Each share costs, say, R$ 100 — and you buy as many as you want through your brokerage app.
That's a Brazilian REIT (Fundo de Investimento Imobiliário / FII): a co-ownership vehicle of real investors, owning actual real estate. Every month, the rent those properties generate is distributed among shareholders. You receive your proportional share in cash, credited to your brokerage account.
That monthly "rent" (called a distribution) is exempt from income tax for individual investors. If you owned a rental property, you'd pay income tax on the rent — in a REIT, you don't. That's why REITs are so popular for passive income.
🏷️ How to recognize a Brazilian REIT (the ticker)
Every Brazilian REIT trades under a ticker (code) with an easy pattern: 4 letters + the number 11. Whenever you see a code ending in 11, it's a real estate fund.
MXRF11 HGLG11 XPML11 KNRI11 VISC11
🧱 Types of Brazilian REITs
Not every REIT owns physical property. There are different families:
- Brick REITs: own physical properties — malls, logistics warehouses, office floors, hospitals. Income comes from renting those properties.
- Paper REITs: don't own property; they lend money to the real estate sector by buying debt securities (CRI — Brazilian mortgage-backed securities). Income comes from the interest on those securities. They tend to yield more when interest rates are high.
- FOF (Fund of Funds): buys shares of other REITs. A way to diversify across many funds by owning just one.
- Hybrid REITs: mix brick and paper.
⚙️ P/BV — the number every investor watches
There's a key indicator to know if a REIT is "expensive" or "cheap": the P/BV (Price-to-Book Value). It compares the share price on the exchange to the fund's actual net asset value.
- P/BV = 1.00 → the share costs exactly the value of the underlying properties.
- P/BV below 1.00 (e.g. 0.90) → you're buying the properties for less than they're worth. Could be an opportunity.
- P/BV above 1.00 (e.g. 1.15) → you're paying a premium over net assets. Sometimes justified by management quality.
Alongside P/BV, look at the dividend yield (annual income relative to price) and the quality of the properties and management.
🛡️ The risk
Brazilian REITs are variable-income assets: the share price fluctuates daily on the exchange. The main risks are:
- Vacancy: if the properties sit empty, rent (and your distributions) falls.
- High interest rates: with Brazil's Selic rate high, fixed income competes and REIT prices tend to drop.
- Default: in paper REITs, defaults on the underlying securities reduce income.
Monthly distributions are not guaranteed — they vary with properties and the market. That's why it's worth diversifying across several funds and types.
✓ When it makes sense
For those wanting monthly passive income and real estate exposure without buying an entire property. Great when buying quality funds at attractive P/BV and holding long term.
✗ When to avoid
Buying solely for a "high dividend" without checking the fund's health, or concentrating everything in a single REIT. This is not an emergency fund — the price fluctuates.
On this site each REIT has a complete, up-to-date analysis — P/BV, distributions, CVM documents and a score. When you're ready to move from "what is it" to "is it worth it?", just look it up.